
If you are house-hunting right now, one question probably keeps circling back: is Academy Mortgage a good lender to actually use, or is it just another big national name with a polished website? That is a fair thing to ask before you hand over your pay stubs and your credit score. In this review we walk through what Academy Mortgage offers, who it fits, where it can frustrate borrowers, and how to make sure you get a competitive deal if you decide to move forward.
A quick, honest note up front: this article is informational only. It is not personalized financial or mortgage advice. Every borrower’s situation is different, so you should always compare at least two or three lenders and talk to a licensed loan officer before you lock anything in. We do not promise specific rates or approval, because no honest reviewer can.
PrimeVouch Score: 8.2 / 10
Best for: First-time buyers, VA-eligible borrowers, and people who want a real human loan officer at a local branch rather than a purely app-based, faceless process.
What we loved:
- A genuinely broad loan menu, including conventional, FHA, VA, USDA, jumbo, ARM, refinance, and renovation options.
- A large branch network with hundreds of local offices, so many borrowers can meet a loan officer in person.
- Long track record: the company has been lending since 1988 and is licensed across nearly the entire country.
- Strong reputation for personable, communicative loan officers in a large volume of customer reviews.
- Solid support for first-time buyers, veterans, and lower-down-payment government loan programs.
Watch out for:
- Rates and fees are not published up front, so you have to request a quote to compare.
- Loan servicing can be transferred to another company after closing, which some borrowers dislike.
- Experience quality varies by branch and by individual loan officer.
- A minority of reviews cite communication or transparency issues, so vetting your specific officer matters.
- It is a retail lender, not a discount online shop, so it will not always be the absolute cheapest option.
Get started with Academy Mortgage
What makes Academy Mortgage different
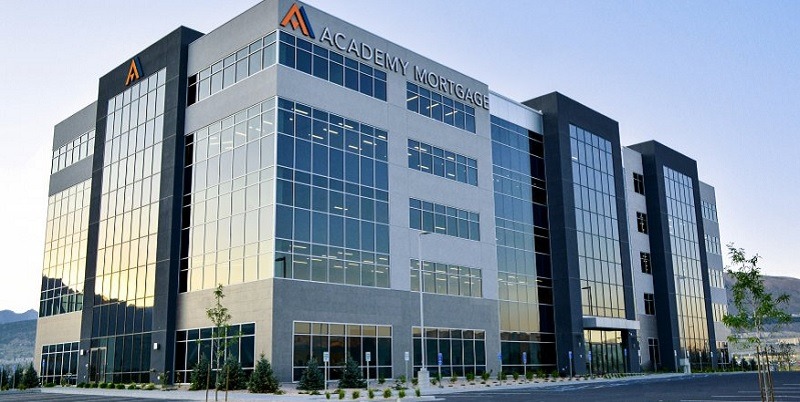
Academy Mortgage is one of the larger independent residential mortgage lenders in the United States. It was founded in 1988 and has grown to hundreds of branch offices, with licensing to originate loans in nearly every state plus the District of Columbia. In recent years the company became part of Guild Mortgage, one of the country’s established retail lenders, which broadened its resources and footprint further.
The thing that actually sets Academy apart is its model. It is a branch-based retail lender, not a pure online broker. That means when you apply, you are usually paired with a local loan officer who owns your file from application to closing. For a lot of borrowers, especially first-timers, that human relationship is the whole point. A mortgage is likely the biggest transaction of your life, and being able to call, email, or sit down with someone who knows your file is worth a great deal.
At the same time, Academy has invested in an online application and document-upload experience, so you are not stuck faxing paperwork. In practice you get a blend: modern digital convenience layered on top of a traditional, relationship-driven process. That hybrid is the core of its appeal, and understanding it helps set the right expectations.
Loan types offered
One of Academy Mortgage’s real strengths is the breadth of its loan menu. Most borrowers will find a program that fits their situation. Here is what the lender offers.
- Conventional loans for buyers with solid credit and a standard down payment who want a straightforward, widely available mortgage.
- FHA loans for first-time or repeat buyers who have a lower credit score or want a smaller down payment. These government-backed loans are a common entry point to homeownership.
- VA loans for eligible veterans, active-duty service members, and certain military families, often with no down payment required. Academy has a strong reputation with military borrowers.
- USDA loans for low- to moderate-income buyers purchasing or building in eligible rural areas, which can allow a zero-down-payment structure.
- Jumbo loans for higher-priced homes that exceed conventional conforming loan limits, available with fixed terms for well-qualified buyers.
- Adjustable-rate mortgages (ARMs) where the rate stays fixed for an initial period, such as five years, and then adjusts periodically afterward.
- Refinance loans for homeowners who want a lower rate, a different term, a lower monthly payment, or cash out from their home equity.
- Renovation loans that let you finance a home purchase and improvement costs together, useful for fixer-uppers.
- State and local housing programs that pair with down payment assistance and first-time-buyer initiatives where available.
That range means Academy can serve everyone from a first-time FHA buyer with limited savings to a jumbo borrower buying a high-value primary residence. Few lenders cover this much ground under one roof.
See which loan fits you at Academy Mortgage
The rest of the range / services
Local branch loan officers
Academy’s hundreds of branches mean you can often work with a loan officer in or near your own community, someone who understands local market conditions and can meet face to face if you prefer.
Online application and document upload
You can start an application, upload documents, and track progress digitally, so the process is not stuck in the paper era even though it is relationship-driven.
Homebuyer education resources
The lender publishes articles, videos, and tools aimed at helping buyers understand the process, which is genuinely useful for first-timers who do not yet know the vocabulary.
Down payment assistance guidance
Because it participates in various state and local housing programs, Academy can help eligible buyers combine assistance programs with their loan.
Refinance and equity options
Existing homeowners can refinance for a better rate or term, or tap equity through a cash-out refinance where it makes sense for their goals.
How the process works / how to get the best rate
The Academy Mortgage process follows the familiar arc of a retail mortgage, with a personal loan officer guiding you at each step.
- Pre-approval. You share income, assets, and credit information, and the lender tells you what you can likely borrow. A pre-approval letter strengthens your offers when you shop for homes.
- Application. Once you have a property, you complete a full application and upload documents such as pay stubs, tax returns, and bank statements.
- Processing and underwriting. The lender verifies your information, orders an appraisal, and an underwriter reviews the full file for approval.
- Closing. You sign final documents, pay closing costs and any down payment, and the loan funds.
To get the best rate you can from Academy, or any lender, a few habits matter. Improve your credit score before applying, since it directly influences your rate. Keep your debt-to-income ratio in check by not taking on new loans right before you buy. Save for a larger down payment when possible, because more equity often means better pricing. And critically, request a written Loan Estimate and compare it against quotes from at least two other lenders. Rates and fees are negotiable more often than borrowers assume, and competing quotes give you leverage.
Watch: Academy Mortgage explained
Before you evaluate any lender, it helps to understand how a mortgage actually works. The short educational video below breaks down the fundamentals of mortgage loans in plain language, which makes it far easier to ask Academy Mortgage the right questions.
Academy Mortgage vs alternatives
No single lender is right for everyone. Here is how Academy Mortgage compares to two common alternative routes so you can see where it fits.
| Route | Best for | Trade-off |
|---|---|---|
| Academy Mortgage | Borrowers who want a broad loan menu and a local, relationship-driven loan officer | Rates not published up front; loan may be serviced by another company later |
| Large online lender | Tech-savvy borrowers who want a fast, app-first process and instant online quotes | Less personal guidance; can feel impersonal for complex situations |
| Local bank or credit union | Existing customers who value relationship pricing and in-house servicing | Narrower loan menu; may lack specialized government-loan expertise |
The honest takeaway is that Academy sits between the pure-online shops and the small local bank. You get more product breadth and reach than most credit unions, with more human contact than most app-only lenders. If price is the only thing you care about, always gather competing quotes regardless of which route you lean toward.
Rates, fees & value
Academy Mortgage does not publish live rates or a standard fee schedule on its site, which is common for retail lenders but means you cannot comparison-shop from the homepage alone. To get real numbers, you request a quote and receive a Loan Estimate, the standardized federal disclosure that lays out your rate, monthly payment, and itemized closing costs.
On value, the picture is nuanced and honest. As a full-service retail lender with local staff, Academy carries the overhead that comes with that model, so it will not always be the rock-bottom cheapest option compared with a bare-bones online lender. What you are paying for is guidance, program breadth, and a person who manages your file. For many borrowers, especially first-timers or those with a less-than-simple financial picture, that support genuinely earns its cost. For a borrower with pristine credit and a simple W-2 income who just wants the lowest number, an online lender might edge it out. The only way to know for your situation is to compare Loan Estimates side by side. We will not invent specific rates or fee figures here, because those change constantly and depend entirely on your profile and the market.
Who should use it — and who should not
Academy Mortgage is a strong fit if you are a first-time buyer who wants hand-holding, a veteran or service member using a VA loan, a rural buyer exploring USDA options, or anyone who simply prefers a local loan officer over a chatbot. Its broad program menu also makes it a good candidate if your situation is a bit unusual, such as needing a renovation loan or pairing a mortgage with down payment assistance.
It is a weaker fit if you are a rate-only shopper with a simple, strong financial profile who is comfortable doing everything online and chasing the absolute lowest cost. In that case you should still get an Academy quote, but weigh it hard against lean online competitors. It may also frustrate you if the idea of your loan being sold to a different servicer after closing bothers you, since that can happen with many lenders including Academy.
Honest limits
To keep this review straight, here are the real limitations. First, transparency on pricing is limited before you apply, so there is some legwork to compare. Second, experience quality is not uniform: because so much rides on your individual branch and loan officer, one borrower’s excellent experience does not guarantee yours. A minority of customer reviews across public platforms mention communication gaps, servicing hiccups, or a mismatch between expectations and outcomes, and those are worth taking seriously even amid a largely positive review body. Third, as a relationship-based retail lender, it is not built to be the cheapest lender on the block. None of this makes Academy a bad choice, but going in with clear eyes, and comparing quotes, protects you.
Academy Mortgage offers & getting started
If Academy Mortgage sounds like the right kind of lender for you, the sensible next step is to get a personalized quote so you have real numbers to compare. Starting with a pre-approval costs you nothing and gives you a clearer budget plus a stronger position when you make an offer on a home. From there, you can weigh Academy’s Loan Estimate against a couple of competitors and make a confident, informed decision.
Get started with Academy Mortgage
Remember to lean on your loan officer for questions, ask for everything in writing, and never feel pressured to lock before you are comfortable. A good lender will welcome your comparison shopping, not discourage it.
Get your Academy Mortgage quote
Frequently asked questions
Is Academy Mortgage a legitimate, established lender?
Yes. Academy Mortgage has operated since 1988, is licensed to lend across nearly every state plus Washington, D.C., and is now part of Guild Mortgage. It holds a strong rating with the Better Business Bureau and has a large volume of customer reviews.
What credit score do I need for Academy Mortgage?
There is no single universal number, because requirements vary by loan program. Government-backed loans like FHA typically allow lower scores than conventional loans, while jumbo loans expect stronger credit. Your loan officer can tell you where you stand for the program you want. This is general information, not personalized advice.
Does Academy Mortgage offer VA and USDA loans?
Yes. Academy offers VA loans for eligible veterans and service members, and USDA loans for eligible buyers in qualifying rural areas, alongside conventional, FHA, jumbo, ARM, refinance, and renovation options.
Will my loan be sold or transferred after closing?
It can be. Like many lenders, Academy may transfer the servicing of your loan to another company after closing. Your loan terms do not change, but you may end up making payments to a different servicer. Ask your loan officer about servicing before you close if this matters to you.
Does Academy Mortgage publish its rates online?
No. Academy does not display live rates or a standard fee schedule on its website. You request a quote and receive a Loan Estimate with your personalized rate and itemized costs, which is the document you should use to compare lenders.
Is Academy Mortgage the cheapest lender?
Not necessarily. As a relationship-driven retail lender, it may not always beat bare-bones online competitors on price. Its value is in guidance and program breadth. Always compare its Loan Estimate against at least two other lenders to be sure.
How to shop for a mortgage and compare APR the smart way
Whether or not you choose Academy Mortgage, knowing how to shop protects your money. Start by getting pre-approved with more than one lender within a short window, typically two to three weeks, so the credit inquiries are treated as a single event by scoring models and your score is minimally affected. Then gather a Loan Estimate from each lender. This standardized form makes side-by-side comparison genuinely possible.
When you compare, look beyond the interest rate to the APR, or annual percentage rate. The APR folds in many of the loan’s costs, such as certain fees and points, into a single annualized figure, so it usually reflects the true cost of borrowing better than the headline rate alone. A loan with a slightly lower rate but heavy fees can carry a higher APR than a loan with a marginally higher rate and low fees. Also compare the itemized closing costs, the loan term, and whether the rate is fixed or adjustable, since an ARM’s low intro rate can rise later.
Finally, ask each lender to explain any fee you do not recognize, and do not be shy about using one lender’s quote to negotiate with another. Mortgage pricing has more flexibility than most people realize. Taking a few extra hours to compare properly can save you thousands of dollars over the life of the loan. And once more, for anything specific to your finances, consult a licensed loan officer or a qualified financial professional, because this article is educational and not personalized advice.